
The global pain management drugs market is entering a period of strategic change as healthcare providers seek effective pain relief, pharmaceutical companies develop alternatives to conventional opioids, and manufacturers expand portfolios across acute, postoperative, neuropathic and chronic pain conditions. Demand is supported by an aging population, increasing surgical procedures, chronic musculoskeletal disorders, cancer-related pain and migraine, alongside broader access to pharmaceutical treatment.
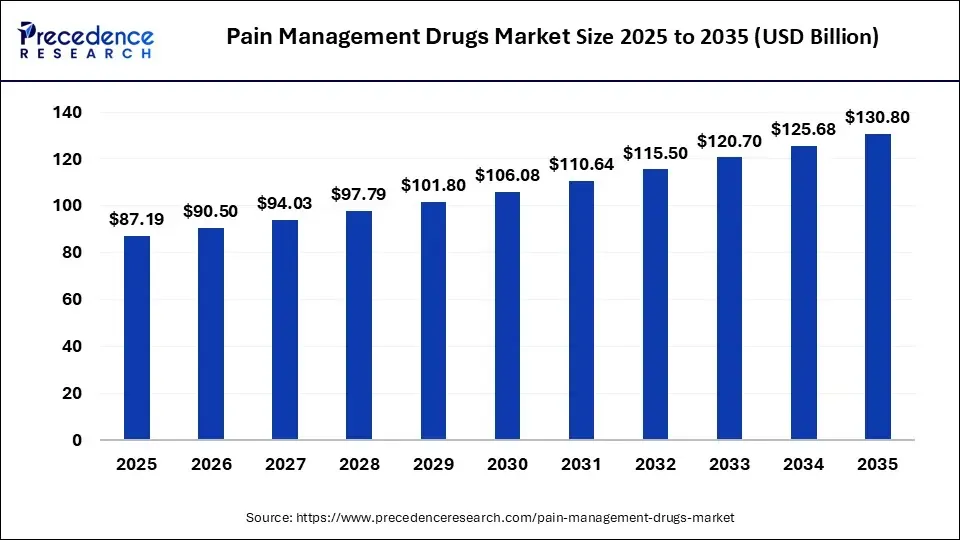
Ottawa, Oct. 30, 2026 (GLOBE NEWSWIRE) -- According to Precedence Research, the global pain management drugs market was valued at USD 87.19 billion in 2025 and is projected to increase from USD 90.50 billion in 2026 to approximately USD 130.80 billion by 2035, registering a compound annual growth rate (CAGR) of 4.14% from 2026 to 2035.
For samples, case studies and examples, fill out the form on the report page or contact Precedence Research to discuss a customized intelligence requirement: https://www.precedenceresearch.com/sample/2494
The market opportunity extends beyond traditional painkillers. Non-opioid analgesics, sodium-channel inhibitors, migraine-specific therapies, extended-release formulations, topical treatments and differentiated postoperative pain products are attracting commercial attention. At the same time, generic competition, medicine pricing, regulatory requirements, safety considerations and the difficulty of demonstrating clinical efficacy continue to shape profitability.
Recent industry developments reinforce this transition. In October 2026, Viatris announced an agreement to acquire Pacira BioSciences for approximately USD 1.65 billion, expanding its portfolio of differentiated non-opioid pain treatments. In February 2026, industry analysis highlighted a pipeline of hundreds of investigational pain medicines, including candidates targeting mechanisms beyond conventional opioids. These developments underscore the importance of innovation, portfolio diversification and market access in shaping the next phase of competition.
How Large Is the Pain Management Drugs Market?
| Market Indicator | Value |
| Global market size, 2025 | USD 87.19 billion |
| Global market size, 2026 | USD 90.50 billion |
| Forecast market size, 2035 | USD 130.80 billion |
| CAGR, 2026–2035 | 4.14% |
| Leading regional market | North America |
| Major drug classes | NSAIDs, opioids, anesthetics, antidepressants and anticonvulsants |
| Key distribution channels | Retail pharmacies, hospital pharmacies and online pharmacies |
Email: sales@precedenceresearch.com
The forecast reflects an established market with a large base of generic medicines and continuing demand for prescription and over-the-counter pain relief. Growth is supported by chronic pain prevalence, healthcare expenditure, surgical care, expanding pharmacy access and advances in targeted treatments.
However, the market is not homogeneous. Conventional analgesics compete largely on availability, affordability, brand recognition and manufacturing efficiency, while innovative therapies compete on clinical outcomes, differentiated mechanisms, tolerability, dosing convenience and reimbursement access.
For pharmaceutical companies, this creates two parallel opportunities: strengthening cost-efficient portfolios of established medicines and investing in differentiated treatments that address unmet needs in selected patient populations.
What Is the Pain Management Drugs Market Share by Drug Class?
Drug class is a central dimension of competition because different medicines address distinct pain mechanisms and clinical requirements. NSAIDs are widely used for inflammatory and musculoskeletal pain, while opioids remain important in selected moderate-to-severe pain settings. Antidepressants and anticonvulsants also have established roles in certain neuropathic pain conditions.
Pain Management Drugs Market by Drug Class 2026 Share and Market Value
The following table presents illustrative analyst estimates, not official Precedence Research segment-share figures. Shares are modeled to provide a complete 2026 allocation and should be validated against a consistent, detailed segment dataset before being used for financial modeling.
| Drug Class | Modeled 2026 Share | Estimated 2026 Market Value |
| Opioids | 30.0% | USD 27.15 billion |
| Non-steroidal anti-inflammatory drugs (NSAIDs) | 26.0% | USD 23.53 billion |
| Anticonvulsants | 12.0% | USD 10.86 billion |
| Antidepressants | 11.5% | USD 10.41 billion |
| Anesthetics | 5.5% | USD 4.98 billion |
| Other pain management drugs | 15.0% | USD 13.57 billion |
Opioids: Opioids continue to serve specific acute, postoperative, cancer-related and other severe-pain needs. Their commercial outlook is influenced by prescribing controls, safety monitoring, generic competition and efforts to reduce unnecessary exposure. Manufacturers must balance clinical requirements with regulatory and supply-chain responsibilities.
NSAIDs: Ibuprofen, naproxen, diclofenac and other NSAIDs are used for a range of inflammatory and musculoskeletal conditions. Established demand, multiple dosage forms and broad distribution support the category. Competition can be intense, making manufacturing costs, formulation quality, brand positioning and retail availability important.
Anticonvulsants and antidepressants: Certain medicines in these classes are prescribed for neuropathic pain and other relevant conditions. Their role illustrates how pain management increasingly depends on the underlying mechanism and patient profile rather than a single universal analgesic approach.
Anesthetics: Local and other anesthetic products are important in surgical procedures and selected acute pain applications. Demand is connected to procedure volumes, hospital purchasing and the adoption of multimodal pain-management protocols.
Other drugs: This category may include nonnarcotic analgesics and other medicines used for particular pain indications. The segment's composition varies according to the market definition and classification method.
What Is the Pain Management Drugs Market Share by Indication?
Pain management medicines are purchased across a wide range of indications, from short-term postoperative recovery to long-term management of neuropathic and musculoskeletal pain. Postoperative pain is a major market opportunity because effective pain control is an important component of surgical recovery.
Pain Management Drugs Market by Indication 2026 Share and Market Value
The following allocation is a modeled estimate for market-sizing illustration. It is not an official Precedence Research indication-share table.
| Indication | Modeled 2026 Share | Estimated 2026 Market Value |
| Postoperative pain | 39.4% | USD 35.66 billion |
| Musculoskeletal pain | 23.3% | USD 21.09 billion |
| Neuropathic pain | 11.4% | USD 10.32 billion |
| Cancer-related pain | 7.9% | USD 7.15 billion |
| Arthritic pain | 7.6% | USD 6.88 billion |
| Chronic back pain | 5.8% | USD 5.25 billion |
| Other indications | 4.6% | USD 4.17 billion |
Postoperative pain: Surgical procedures create demand for short-duration analgesics, local anesthetics and multimodal pain-management regimens. Hospitals and surgical centers assess products according to pain control, tolerability, dosing requirements, recovery protocols and overall treatment costs.
Musculoskeletal and arthritic pain: Aging populations and the burden of joint, muscle and skeletal conditions support sustained demand for pain relief. Product differentiation may come from formulation, duration of effect, route of administration and suitability for specific patient groups.
Neuropathic pain: This category creates opportunities for therapies designed around nerve-related pain mechanisms. Treatment can be challenging because symptoms vary between patients, and effective management may require tailored drug selection and monitoring.
Cancer-related pain: Oncology care can involve complex pain requirements that vary with disease stage, treatment and patient circumstances. Availability, prescribing oversight and coordination between care teams are important factors.
Chronic back pain and other indications: These conditions span diverse patient populations and treatment pathways. Commercial opportunities depend on clinical evidence, physician awareness, access to care and the suitability of a medicine for the intended indication.
Note: Indication classifications can overlap clinically. The table is a mutually exclusive modeled revenue allocation for illustration and should not be interpreted as an official clinical or market dataset.
What Is the Pain Management Drugs Market Share by Distribution Channel?
Distribution channels connect manufacturers with patients and healthcare providers. Retail pharmacies serve demand for many widely used medicines, while hospital pharmacies supply products used in inpatient care, surgery and specialized treatment. Online pharmacies provide an additional channel where local regulations permit and prescriptions can be appropriately verified.
Pain Management Drugs Market by Distribution Channel 2026 Share and Market Value
The following shares are illustrative analyst estimates, not official published channel shares.
| Distribution Channel | Modeled 2026 Share | Estimated 2026 Market Value |
| Retail pharmacies | 48.0% | USD 43.44 billion |
| Hospital pharmacies | 34.0% | USD 30.77 billion |
| Online pharmacies | 18.0% | USD 16.29 billion |
Retail pharmacies: Broad access to common analgesics, established distribution networks and consumer familiarity support this channel. Manufacturers compete through product availability, pricing, brand recognition, packaging and relationships with pharmacy chains and distributors.
Hospital pharmacies: Hospitals purchase medicines for surgical procedures, acute-care treatment and other clinical needs. Procurement decisions may emphasize formulary status, clinical evidence, supply reliability, unit economics and compliance with institutional protocols.
Online pharmacies: Digital ordering can improve convenience and access for eligible products. Growth depends on regulatory permissions, prescription verification, distribution infrastructure, consumer trust and safeguards against inappropriate medicine supply.
Channel shares differ by geography, prescription status and the mix of products included in a market definition. The estimates above should be treated as a directional framework rather than a verified market measurement.
How Is Non-Opioid Innovation Changing the Competitive Landscape?
One of the most important developments in pain therapeutics is the search for alternatives that can deliver effective pain relief without relying on opioid mechanisms.
In January 2025, the U.S. Food and Drug Administration approved JOURNAVX (suzetrigine), a non-opioid treatment for moderate-to-severe acute pain in adults. The medicine targets the NaV1.8 voltage-gated sodium channel, a mechanism involved in pain-signal transmission. Its introduction has increased attention on sodium-channel inhibitors and other approaches that could complement established treatments.
Innovation does not remove the challenges of drug development. Pain is subjective, patients may experience several pain mechanisms simultaneously, and clinical trials can face substantial placebo responses. Developers must demonstrate meaningful benefits for specific populations while establishing safety, tolerability, dosing and appropriate use.
The commercial opportunity therefore depends on more than a novel mechanism. Pharmaceutical companies need to show how a treatment compares with existing options, which patients are most likely to benefit, whether it can secure reimbursement and how its price aligns with clinical value.
Other areas of innovation include extended-release formulations, topical and transdermal delivery, local anesthetics, migraine-specific therapies and combination products. These approaches can address dosing convenience, targeted delivery or specific clinical needs, although their benefits must be established for the relevant product and indication.
Which Recent Company Developments Are Shaping the Pain Management Drugs Market?
Viatris Agrees to Acquire Pacira BioSciences
In October 2026, Viatris announced an agreement to acquire Pacira BioSciences for approximately USD 1.65 billion in cash. The transaction is intended to strengthen Viatris's portfolio of differentiated medicines, including EXPAREL for postsurgical pain and ZILRETTA for knee osteoarthritis pain.
The proposed acquisition reflects pharmaceutical companies' interest in products that can help diversify revenue beyond conventional generics. Pacira's portfolio gives Viatris exposure to established non-opioid pain treatments, while its commercial capabilities may support expansion into additional markets, subject to transaction completion, applicable approvals and integration plans.
For competing companies, the deal highlights the strategic value of differentiated formulations, clinical evidence and established prescribing relationships. For suppliers and investors, it also reinforces the importance of evaluating product-level revenue, patent protection, manufacturing requirements and commercialization potential rather than relying on broad market growth alone.
Development Pipelines Expand Beyond Traditional Mechanisms
Industry analysis published in February 2026 reported that hundreds of drug candidates were in development for pain indications, excluding migraine-only candidates. The pipeline included both established drug modalities and therapies directed at newer biological targets.
This activity creates opportunities for contract development and manufacturing organizations, clinical research providers, active pharmaceutical ingredient suppliers, formulation specialists and companies providing analytical and regulatory services.
However, a large pipeline is not equivalent to future commercial revenue. Candidates must pass clinical and regulatory milestones, demonstrate clinically meaningful efficacy and establish a viable position against existing treatment options.
Pharmaceutical Partnerships Support Product Commercialization
In October 2026, Spektus Pharma and GEBRO Holding announced a partnership to commercialize ActraFlex, an extended-release tramadol and paracetamol formulation, across agreed territories. The arrangement illustrates how formulation technology, regional commercial networks and licensing partnerships can help companies expand product access.
Such partnerships may provide a route to market for companies that lack a complete international distribution infrastructure. Their success depends on regulatory requirements, product differentiation, commercial execution and the ability to compete with existing therapies.
How Do Pricing, Manufacturing Costs and Generic Competition Affect Profitability?
Pain management drugs span low-cost generic tablets, branded prescription medicines, injectable products, topical formulations and specialized therapies. Pricing therefore varies significantly by molecule, formulation, dosage, market, reimbursement system and purchasing channel.
Established generic products often face price competition from multiple suppliers. Manufacturers must control active pharmaceutical ingredient costs, production yields, packaging, quality assurance, regulatory compliance and distribution expenses. Supply interruptions or quality issues can affect availability and increase operating costs.
Differentiated products may support higher prices when they demonstrate relevant clinical benefits, improved delivery, convenient dosing or value in a defined treatment pathway. However, premium pricing is not guaranteed: payers and providers assess clinical evidence, alternatives, budget impact and reimbursement criteria.
Hospital purchasing can be particularly sensitive to formulary decisions, contract terms and supply reliability. Retail sales are affected by brand recognition, pharmacy distribution and competition among equivalent products. Online channels introduce additional considerations around fulfillment, regulatory compliance and customer acquisition.
For commercial planning, manufacturers should monitor:
- Active pharmaceutical ingredient prices and supplier concentration.
- Manufacturing utilization, batch yields and quality-related costs.
- Generic entry, patent expiry and product substitution.
- Hospital tenders, pharmacy purchasing contracts and formulary decisions.
- Regulatory changes affecting production, labeling and distribution.
- Product-level sales, reimbursement status and market access.
- Demand for differentiated delivery systems and non-opioid alternatives.
Reliable public data on transaction-level prices and manufacturer margins is not available consistently across the global market. Consequently, precise global average selling prices or profit margins should not be inferred from the market forecast alone.
Which Companies Are Competing in the Pain Management Drugs Market?
Competition includes pharmaceutical innovators, generic-drug manufacturers, consumer healthcare businesses and companies specializing in postoperative or localized pain treatments.
| Company | Core Market Focus | Competitive Positioning and Opportunity |
| Pfizer | Prescription medicines and selected pain-related therapies | Established pharmaceutical capabilities and global commercial reach |
| Teva Pharmaceutical Industries | Generic and specialty medicines | Broad generic portfolio and opportunities in differentiated formulations |
| Viatris | Generics and branded medicines | Portfolio diversification and expansion into differentiated pain treatments |
| AbbVie | Specialty pharmaceuticals and migraine-related therapies | Exposure to targeted therapies and established specialty-care channels |
| Eli Lilly and Company | Innovative medicines and pain-related research | Opportunity to develop new mechanisms and build differentiated pipelines |
| Vertex Pharmaceuticals | Innovative non-opioid pain therapies | NaV1.8 inhibitor development and commercialization of JOURNAVX |
| Haleon | Consumer healthcare and over-the-counter pain relief | Consumer brands, retail distribution and topical pain-relief products |
| Bayer | Consumer health and pharmaceutical products | Established nonprescription pain-relief brands and broad market access |
| Kenvue | Consumer health and analgesic products | Retail reach and established consumer pain-relief brands |
| Grünenthal | Pain-focused medicines and pain management | Specialist experience and products for selected pain conditions |
| Pacira BioSciences | Non-opioid pain management products | Differentiated postoperative and osteoarthritis pain treatments; proposed acquisition target |
| Hikma Pharmaceuticals | Generic and injectable medicines | Hospital channel relationships and established pharmaceutical manufacturing |
| Sun Pharmaceutical Industries | Generic and specialty pharmaceuticals | Broad international footprint and formulation capabilities |
| Dr. Reddy's Laboratories | Generic and specialty medicines | Cost-efficient manufacturing and market access across multiple regions |
| Tonix Pharmaceuticals | Development of medicines for selected pain conditions | Opportunity to commercialize differentiated treatments and develop specialty indications |
Competitive position varies by product and indication. A company with strong over-the-counter brands may not have the same capabilities in hospital injectables or innovative prescription therapies. Likewise, a large pharmaceutical company may have only a limited share of the pain management drugs market.
For strategic planning, companies should assess product-level sales, patent and exclusivity periods, clinical pipeline milestones, regulatory status, manufacturing capacity, geographic distribution, market access and the strength of competing treatments.
What Are the Regional Opportunities in the Pain Management Drugs Market?
North America is the leading regional market in the supplied Precedence Research analysis, supported by high healthcare spending, established pharmaceutical distribution and demand for treatments for chronic and acute pain. Asia Pacific offers growth potential as healthcare access expands and pharmaceutical manufacturing and distribution networks develop.
The following regional figures are illustrative modeled shares, not official Precedence Research regional-share estimates. They should be validated against a consistent regional dataset before external publication as market measurements.
Pain Management Drugs Market by Region 2026 Share and Market Value
| Region | Modeled 2026 Share | Estimated 2026 Market Value |
| North America | 44.0% | USD 39.82 billion |
| Europe | 22.4% | USD 20.27 billion |
| Asia Pacific | 23.1% | USD 20.91 billion |
| Latin America | 5.8% | USD 5.25 billion |
| Middle East & Africa | 4.7% | USD 4.25 billion |
North America: The United States is a major market because of its healthcare expenditure, pharmaceutical infrastructure and demand for acute, chronic and postoperative pain treatments. Competition is influenced by reimbursement, generic substitution, prescribing controls and the adoption of innovative non-opioid medicines.
Europe: Established healthcare systems and pharmaceutical distribution support access to both conventional and innovative treatments. Regulatory requirements, reimbursement decisions, national healthcare budgets and concerns about opioid-related harm influence market access.
Asia Pacific: China, India, Japan and other regional markets offer opportunities linked to expanding healthcare services, increasing treatment access and established pharmaceutical manufacturing. Local pricing, regulatory pathways and distribution partnerships remain important considerations.
Latin America: Brazil, Mexico and other markets present opportunities for manufacturers with reliable distribution, competitive pricing and local regulatory expertise. Affordability and access to healthcare can influence adoption.
Middle East & Africa: Expanding healthcare infrastructure and pharmaceutical procurement create opportunities for suppliers. Market development depends on medicine availability, local registration, distribution networks and the ability to meet healthcare-system requirements.
Regional opportunity should be evaluated by product and indication. A medicine's commercial performance in one country does not automatically translate to another because prescribing practices, reimbursement, regulatory requirements and purchasing power differ.
How Can Market Intelligence Help Generate B2B Leads?
Pain management drugs create commercial opportunities across pharmaceutical manufacturing, contract development, clinical research, distribution, licensing and product commercialization. Lead generation is most effective when companies identify specific purchasing or partnership signals rather than approaching all pharmaceutical organizations in the same way.
| Target Account Group | Relevant Decision-Makers | Purchase or Expansion Signals | Potential Commercial Opportunity |
| Pharmaceutical innovators | CEO, R&D head, portfolio strategy director | New candidates, pipeline expansion, licensing activity | Market assessment, competitive intelligence and commercialization planning |
| Generic-drug manufacturers | Business unit head, manufacturing director, commercial lead | New product registrations, capacity additions, patent expiry | Product opportunity assessment and competitor benchmarking |
| API and formulation suppliers | Business development director, technical sales head | New customer qualification, production expansion, supply agreements | Supplier intelligence and account development |
| Contract development and manufacturing organizations | Commercial director, site head, program director | Outsourcing announcements, new facilities, clinical-stage demand | Partnership mapping and demand forecasting |
| Hospital and specialty distributors | Procurement head, distribution director | New formulary listings, tender opportunities, geographic expansion | Channel analysis and target-account identification |
| Consumer healthcare companies | Brand director, category manager, sales leader | Product launches, retail expansion, portfolio acquisitions | Brand benchmarking and retail-channel intelligence |
| Biotechnology companies | Chief scientific officer, alliance director, licensing lead | Clinical milestones, fundraising, partnership searches | Pipeline mapping and licensing opportunity assessment |
| Investors and corporate development teams | Investment director, corporate development executive | Acquisitions, divestitures, portfolio restructuring | Due diligence support and company-level analysis |
Useful buying signals include clinical trial milestones, regulatory submissions, new product approvals, licensing agreements, manufacturing expansions, acquisitions, tender awards and market-entry announcements. Mapping these events against company capabilities and regional demand can help commercial teams prioritize prospects and partnership opportunities.
Precedence Research offers market sizing, company profiling, segment analysis, regional assessment, competitive benchmarking and customized research to support these activities. Its Master Dataset, Precedence Quadrant, Interactive Intelligence Dashboard, Quality & Manufacturing Intelligence and Customized Research can help organizations evaluate target accounts, compare competitors, identify market opportunities and strengthen go-to-market planning. Research updates can be arranged monthly, quarterly, every six months or annually according to the business requirement.
What Should Businesses Monitor Through 2035?
The pain management drugs market is expected to expand steadily, but the strongest commercial opportunities will differ across generic products, innovative medicines, hospital-use treatments and consumer healthcare brands.
Companies should monitor the adoption of non-opioid therapies, clinical and regulatory milestones, product-level sales, pricing pressure, patent expirations, manufacturing costs, reimbursement changes and pharmaceutical acquisitions. They should also evaluate whether new therapies offer meaningful clinical differentiation and whether manufacturers can establish reliable supply and appropriate market access.
For investors, pipeline quality, clinical success probabilities, regulatory risk, intellectual property, commercialization costs and competitive alternatives are central considerations. For manufacturers, operational efficiency, product quality, supplier resilience and portfolio selection remain important. For business development teams, account intelligence and verified commercial signals can improve prospect prioritization.
Precedence Research's market study provides a framework for assessing the global market forecast, drug classes, indications, distribution channels and regional opportunities. Customized research can further examine selected products, companies, countries, customer segments and commercial questions.
Related Reports
The following related Precedence Research pages cover the pain management market and adjacent pharmaceutical and analgesics categories.
- U.S. Pain Management Drugs Market - https://www.precedenceresearch.com/us-pain-management-drugs-market
- North America Pain Management Drugs Market - https://www.precedenceresearch.com/databook/north-america-pain-management-drugs-market
- Europe Pain Management Drugs Market - https://www.precedenceresearch.com/databook/europe-pain-management-drugs-market
- Asia Pacific Pain Management Drugs Market - https://www.precedenceresearch.com/databook/asia-pacific-pain-management-drugs-market
- Middle East and Africa Pain Management Drugs Market - https://www.precedenceresearch.com/databook/mea-pain-management-drugs-market
- U.S. Pharmaceutical Market - https://www.precedenceresearch.com/databook/us-pharmaceutical-market
- Pharmaceutical Market - https://www.precedenceresearch.com/pharmaceutical-market
- Asia Pacific Analgesics Market - https://www.precedenceresearch.com/databook/asia-pacific-analgesics-market
- Middle East and Africa Analgesics Market - https://www.precedenceresearch.com/databook/mea-analgesics-market
- Pain Management Therapeutics Market - https://www.precedenceresearch.com/pain-management-therapeutics-market
- U.S. Analgesics Market - https://www.precedenceresearch.com/databook/us-analgesics-market
- Europe Analgesics Market - https://www.precedenceresearch.com/databook/europe-analgesics-market
- North America Analgesics Market - https://www.precedenceresearch.com/databook/north-america-analgesics-market
- U.S. Analgesics Market - https://www.precedenceresearch.com/us-analgesics-market
- Migraine Drugs Market - https://www.precedenceresearch.com/migraine-drugs-market
- Non-Opioid Pain Management Market - https://www.precedenceresearch.com/non-opioid-pain-management-market
- Neuropathic Pain Market - https://www.precedenceresearch.com/neuropathic-pain-market
- Opioids Market - https://www.precedenceresearch.com/opioids-market
- Non-Steroidal Anti-Inflammatory Drugs Market - https://www.precedenceresearch.com/non-steroidal-anti-inflammatory-drugs-market
About Precedence Research
Precedence Research provides market intelligence, industry forecasts, competitive analysis, company profiling, customer intelligence and customized research to help organizations evaluate growth opportunities and make informed strategic decisions. Its research supports market entry, commercialization, buyer intelligence, competitor assessment, investment planning and go-to-market strategy.
Explore the report: https://www.precedenceresearch.com/pain-management-drugs-market
Schedule a meeting: https://www.precedenceresearch.com/schedule-meeting
Connect With Us
Email: sales@precedenceresearch.com
Phone
- USA: +1 804 441 9344
- APAC: +61 485 981 310
- India: +91 87933 22019
- Singapore: +65 3105 1271
- Europe: +44 7383 092 044
Social Media
- LinkedIn: https://www.linkedin.com/company/precedence-research
- Facebook: https://www.facebook.com/precedenceresearch
- X: https://x.com/precedence_r
- Medium: https://precedence-research.medium.com/
Partner Platforms
- Towards Healthcare: https://www.towardshealthcare.com/
- Towards Packaging: https://www.towardspackaging.com/
- Towards Chemical & Materials: https://www.towardschemandmaterials.com/
For samples, case studies and examples, fill out the form on the report page or contact Precedence Research to discuss a customized intelligence requirement: sales@precedenceresearch.com

Comments (0)
Login to join the conversation
Login / RegisterNo comments yet. Be the first to comment!